Global financial markets are currently navigating a complex environment where a sustained oil price rally is intersecting with a significant surge in sovereign debt yields. As geopolitical tensions in the Middle East escalate, the resulting supply disruptions have pushed energy costs higher, complicating the inflation outlook just as major central banks prepare for pivotal policy decisions [5] [15]. This "stranglehold" on the market has triggered a rotation out of high-growth technology sectors and into defensive assets, while the cryptocurrency market remains volatile ahead of critical legislative and monetary catalysts [17] [21]. Analysts observe that the resilience of the global economy is being tested by the dual pressure of expensive energy and the highest borrowing costs seen in nearly two decades [15] [16].
Current Oil Prices and Geopolitical Supply Shocks
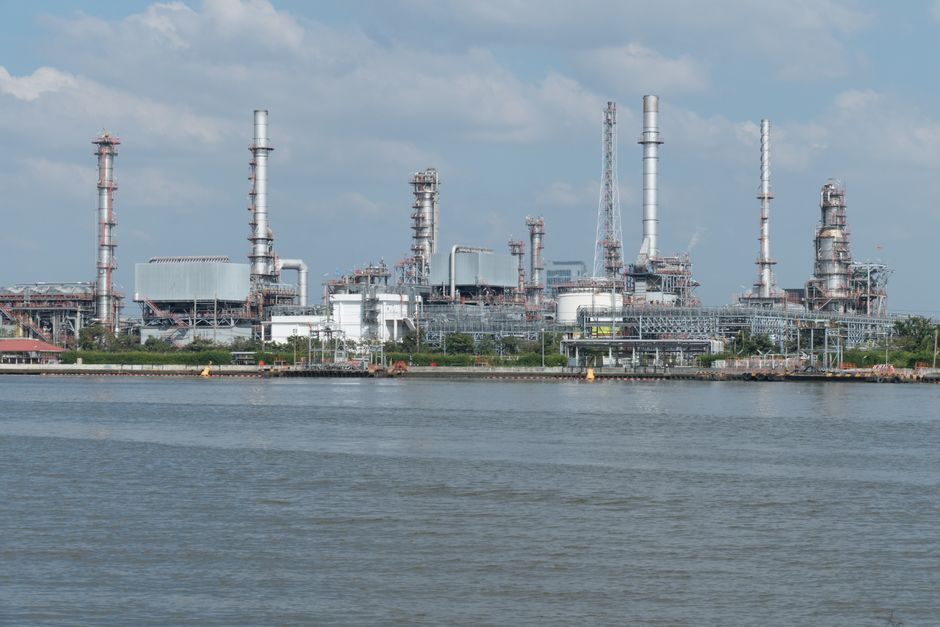
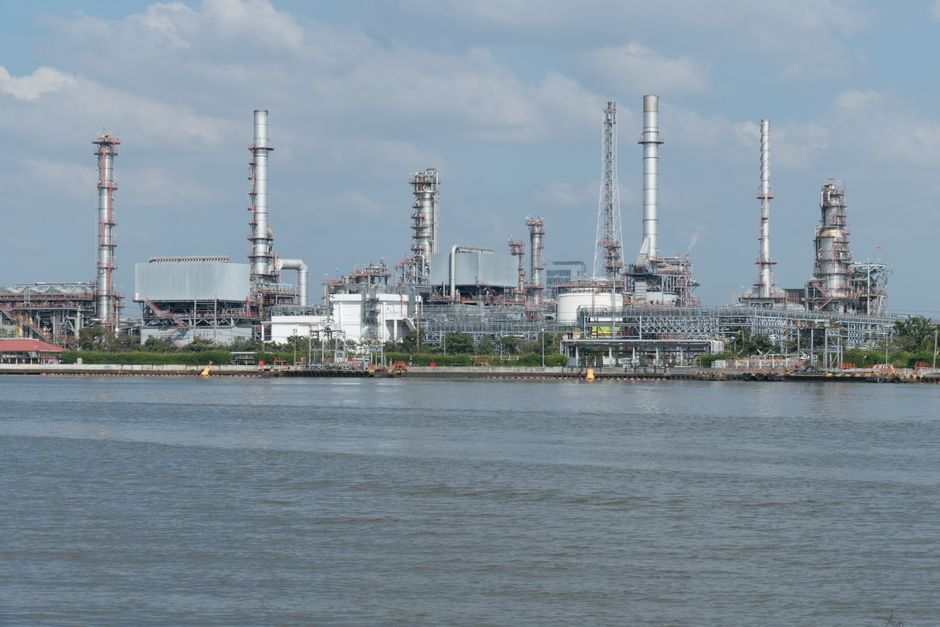
The oil price today reflects a significant risk premium as logistics in the Persian Gulf face unprecedented disruptions. Brent and West Texas Intermediate (WTI) crude prices jumped more than 4.0% to start the week, driven by the near-total closure of the Strait of Hormuz and the forced shutdown of Saudi Arabia’s East-West oil pipeline following a Houthi drone attack [15] [22]. The brent crude oil price has decisively breached the $100 psychological level, trading as high as $107 to $108 per barrel [22]. This acceleration follows reports that daily shipping traffic through the Strait of Hormuz—a waterway carrying a fifth of global supply—dropped to just 3.33% of its normal flow at one point last week [22].
Market data suggests that the crude oil price is no longer just reacting to Iranian supply concerns but is now pricing in a broader infrastructure shock across the Gulf [22]. Over the weekend, only four commodity vessels were reported to have exited the Strait, significantly below the 10-day average of 14 per day [22]. Furthermore, the postponement of a planned Iran-Gulf meeting has removed an immediate de-escalatory catalyst, keeping oil futures elevated as traders anticipate prolonged volatility [22]. If these supply disruptions continue, some analysts suggest the brent crude oil price could push toward the $115–$120 range, particularly if additional tanker incidents occur [22].
Central Bank Policy and the Surge in Yields
The rising oil price per barrel is adding fresh inflationary pressure, influencing the perceived odds of further monetary tightening. The Federal Open Market Committee (FOMC) began its two-day meeting on September 15, with prediction markets such as Kalshi assigning a 79% to 86% probability to a 25-basis-point interest rate hike [3] [19]. This hawkish sentiment is reinforced by recent data showing the U.S. Consumer Price Index (CPI) rose 0.4% in August, a re-acceleration driven largely by a 2.1% monthly increase in energy costs [19]. While some traders hope for a "higher-for-longer" message that signals the end of the tightening cycle, the immediate backdrop remains one of rising costs and sticky inflation [19].
This environment has sent the U.S. 10-year Treasury yield above the 5.00% benchmark, its highest level since 2007 [10] [16]. Before the 2008 financial crisis, a 5% yield was considered normal, but in the current era, it represents a significant hurdle for growth-sensitive assets [16]. Higher yields increase the opportunity cost of holding non-yielding assets like gold or high-multiple technology stocks, contributing to the recent selloff in the Nasdaq and the S&P 500 [7] [15]. Globally, sovereign debt yields have followed suit, with 10-year yields rising in the U.K., Italy, and Australia as markets brace for a synchronized period of restrictive policy [5] [15].
Divergent Central Bank Actions Globally
While the Federal Reserve and the Bank of England are the primary focus, other central banks are already reacting to regional pressures. The Central Bank of Armenia recently increased its refinancing rate to 6.75% from 6.50%, citing the risks of intensifying inflationary pressures amid regional conflicts [2]. Conversely, the National Bank of Angola reduced its policy rate by a full percentage point to 14.75%, following a consistent deceleration in consumer price inflation from a peak of 31.1% in 2024 to a current low of 8.8% [2]. Meanwhile, the Bank of Japan is expected to raise its policy rate to 1.25% on Friday, which would be its highest level since 1995, as it seeks to normalize policy amid growing inflation risks [8].
Market Impact: From AI Stocks to Bitcoin
The combination of a high crude oil price and surging bond yields has hit the technology sector particularly hard. The Taiwan Index (TAIEX), a major beneficiary of the artificial intelligence cycle, fell approximately 350 points this week as investors reassessed AI capital expenditure sustainability [7]. Major semiconductor players like SK Hynix and TSMC have faced downward pressure, with the former dropping 6% in recent sessions [21]. This "AI-sector selloff" is partly attributed to the rising costs of energy-intensive data centers and the broader inflationary environment [7] [21].
In the digital asset space, Bitcoin has struggled to maintain its momentum, falling below the $76,000 support level [4] [10]. Crude oil futures and rising yields have acted as a "wet blanket" on the crypto market, which is also processing the potential impact of the CLARITY Act [10] [24]. This proposed U.S. legislation seeks to establish a federal framework for digital assets, but odds of it passing the Senate in 2026 recently collapsed from 29.5% to 12.5% on prediction markets like Polymarket [4]. Despite the price decline, some analysts observe a "leverage reset," as Bitcoin open interest fell by 13.5% in ten days, suggesting that traders are proactively reducing risk ahead of the FOMC decision [11].
XRP has also remained range-bound near $1.40, despite its 30-day liquidity index on Binance reaching a six-month high [1] [12]. While deeper liquidity allows for more efficient trading, it does not inherently signal a directional move. XRP currently sits above its 20-day and 200-day Exponential Moving Averages (EMAs), but momentum indicators like the MACD suggest the recent recovery may be losing steam [1] [12]. Traders are closely watching the $1.38 to $1.42 resistance zone, as a decisive breakout could open a path toward $1.60, while a failure to hold support at $1.39 could lead to a retest of the $1.33 level [12] [14].
What to watch next: The market's immediate focus remains on the FOMC policy statement and Chair Kevin Warsh's subsequent press conference on Wednesday afternoon [3] [10]. Investors will be looking for any signs of a shift in the "higher-for-longer" narrative. Additionally, the status of the Saudi East-West pipeline and shipping volumes through the Strait of Hormuz will continue to dictate the oil price and its subsequent impact on global inflation expectations [15] [22].